Property 1 of ARMA(1,1) Processes: The following is true for an ARMA(1,1) process
 Proof: As we saw in Infinite Moving Average

where ψ0 = 1 and for j > 0
 By Property 4 of Infinite Moving Average

Property 2 of ARMA(1,1) Processes: The following is true for an ARMA(1,1) process

and for k > 1
Proof: By Property 4 of Infinite Moving Average


The rest of the proof is by induction on k. First, we note that
By Property 4 of Infinite Moving Average and the induction hypothesis

Property 3 of ARMA(1,1) Processes: The following is true for an ARMA(1,1) process

and for k > 1
 Proof: By Property 1 and 2


Property 2 of ARMA(p,q) Processes: Let
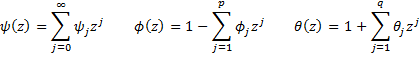
Then
which in turn results in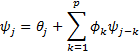
where θ0 = 1, θj = 0 for j > q and ψj = 0 for j < 0.
Proof: Since

If converges, then

In this case, we can find the coefficients in ψ(z) by solving φ(L)ψ(z) = θ(L) as follows:

Multiplying out the left side of the equation and equating coefficients of zj for j = 0, 1, 2, … yields


etc.
which yields the result we are seeking.
Links
References
Greene, W. H. (2002) Econometric analysis. 5th Ed. Prentice-Hall
https://www.ctanujit.org/uploads/2/5/3/9/25393293/_econometric_analysis_by_greence.pdf
Gujarati, D. & Porter, D. (2009) Basic econometrics. 5th Ed. McGraw Hill
https://ucanapplym.s3.ap-south-1.amazonaws.com/RGU/notifications/E_learning/0nline_study/Basic-Econometrics-5th-Ed-Gujarati-and-P.pdf
Hamilton, J. D. (1994) Time series analysis. Princeton University Press
https://press.princeton.edu/books/hardcover/9780691042893/time-series-analysis
Wooldridge, J. M. (2009) Introductory econometrics, a modern approach. 5th Ed. South-Western, Cegage Learning
https://cbpbu.ac.in/userfiles/file/2020/STUDY_MAT/ECO/2.pdf