A p-order autoregressive process, denoted AR(p), takes the form
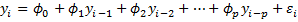
Thinking of the subscripts i as representing time, we see that the value of y at time i is a linear function of y at earlier times plus a fixed constant and a random error term. As for an ordinary linear regression model, we assume that the error terms are independently and normally distributed with zero mean and constant variance σ2, and that the error terms are independent of the y values.
Topics
- Basic Concepts
- Characteristic Equation
- Partial Autocorrelation
- Finding Model Coefficients using ACF/PACF
- Finding Model Coefficients using Linear Regression
- Lag Function Representation
- Augmented Dickey-Fuller Test
- Other Unit Root Tests
Links
References
Greene, W. H. (2002) Econometric analysis. 5th Ed. Prentice-Hall
https://www.ctanujit.org/uploads/2/5/3/9/25393293/_econometric_analysis_by_greence.pdf
Gujarati, D. & Porter, D. (2009) Basic econometrics. 5th Ed. McGraw Hill
https://ucanapplym.s3.ap-south-1.amazonaws.com/RGU/notifications/E_learning/0nline_study/Basic-Econometrics-5th-Ed-Gujarati-and-P.pdf
Hamilton, J. D. (1994) Time series analysis. Princeton University Press
https://press.princeton.edu/books/hardcover/9780691042893/time-series-analysis
Wooldridge, J. M. (2009) Introductory econometrics, a modern approach. 5th Ed. South-Western, Cegage Learning
https://cbpbu.ac.in/userfiles/file/2020/STUDY_MAT/ECO/2.pdf
Dear all sir or madam in here, now i am want to learn about AR, MA, and ARMA. do you a short detail for me to write a documents to teach. may u please kindly.(Rush)
These topics are covered on this website.
Charles
Hello!
I am trying to do Autoregressive Distributed Lag. Is this available in this toolpack?
Hello Mary,
ADL models are not explicitly supported in this toolpak as of yet. Of course, if certain assumptions are met OLS regression (which is supported) can be used. See http://mail.tku.edu.tw/chenyiyi/ADL.pdf (or many other sources).
Charles
Hi Charles, Thank you very much for this site. It is extremely helpful. I would like to find out how you determine the error terms for the ARIMA model (ei).
Kind regards,
Kyle
Kyle,
The formula is of form y_i = [linear combination of y_j terms and coefficients] + e_i. If you know the values of the coefficients and the y_j terms, then the error term is simply e_i = y_i – [linear combination of y_j terms and coefficients].
Charles
explained a very lucid style so that even a beginner could understand. realy good. thank you sir